My blog is going on a little hiatus.
I have been struggling to keep up with things of late - nothing is wrong, but with work and an enormous amount of study, keeping posting unforunately isn't at the high end of my priorities.
At the moment, I work 35 hours a week, and with the number of courses I'm doing, I "meant" to study a crazy 60 hours a week. In about 2 weeks, that will drop back to 36 hours a week as some of my courses are finishing, but with full-time work it's still a struggle. I don't actually study 60 hours per week, but particularly as I took a weekend "off" last week to go away, my life for the last few weeks has been work until 5ish, go home, and work on assignments until anywhere from midnight to 4am because not having studied the amount I should be, I have left them to the last minute.
I'm not closing my blog and hopefully once study cuts down a bit I'll have more time.
I'm still keeping track of my spending, but with my insane hours of late I have been buying too many "little luxuries" - i.e. fast food/magazines etc.
I haven't even updated July figures yet, but a quick overall picture:
I currently have 3 credits cards, owing around $19,000.
Next pay I will get my regular pay plus $2,000 for study costs, so I will be paying off Credit Card 2.
When my tax refund comes through, (i.e. when I finally finish my tax), that should be almost $10K. So I'll pay off Credit Card 3.
Then, it is just Credit Card 4, which has a balance transfer rate.
My aim will be to start the new year with less than $5,000K debt, which is more than achievable.
Showing posts with label Credit cards. Show all posts
Showing posts with label Credit cards. Show all posts
Saturday, August 22, 2009

Sunday, July 12, 2009
June Update
Finally sorted out all my expenses/income for June.
I've updated my sidebars, although I left a credit card statement at work, so I estimated, it is slightly less than I'm showing now. In good news: UNDER $20,000! Still a horrible amount of debt, but I'm slowly getting there.
My income for June was: $3,734.15
Expenses, not including credit card interest, (will update once I get my other credit card statement back from work), were: $2,450.28.
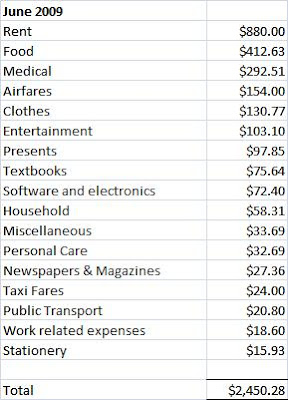
I've updated my sidebars, although I left a credit card statement at work, so I estimated, it is slightly less than I'm showing now. In good news: UNDER $20,000! Still a horrible amount of debt, but I'm slowly getting there.
My income for June was: $3,734.15
Expenses, not including credit card interest, (will update once I get my other credit card statement back from work), were: $2,450.28.

Emergency fund is slowly going up. Savings have taken a hit due to me buying a laptop, so have to start working on those again. It's a new financial year, I've had a horrible start due to being sick, (and still am sick), but need to get much more organised in terms of budgeting/goals etc.
Friday, June 5, 2009
Credit card update May/June
It's going down!!!
On 1 May, I owed $22,016.77
On 1 June, I owed $20,690.52
I have completely paid off Card 1, which is the first card I've gotten rid of without any balance transfers. It was my smallest card, but it also had the highest interest rate.
Next challenge is to Tackle Card 2, it actually has the lowest rate but only until about September (it was a six-month balance transfer off), I need to check the exact date it will expire. I would love to be able to pay it off just through my salary, but if worst comes to worst I should hae a tax refund by then (in Australia our financial year runs from July-June each year).
Tuesday, May 19, 2009
Credit card increases & status
I received another offer to increase one of my credit card limits. So much for the credit crunch. So far this year I've recevied:
- An offer to increase a $12,500 credit card to $19,000
- An offer to increase a $10,000 credit card to $13,000
In addition, a couple of months ago I received an offer to ugrade to a gold credit card (no increase in credit limit). Let's look at the Pros and Cons of the gold credit card, compared to the one I did have with the bank:
Pros
- It was "Gold"
- Balance transfer offer of 3.9%
Cons
- Higher standard interest rate
- High annual fee
I did accept the offer for the Gold card because I made use of the 3.9% balance transfer offer. But if I hadn't needed/wanted the balance transfer offer, the only advantage would be that it was "gold" and this got me thinking about credit card "colours" and status.
Is a gold card really any superior to a normal/standard card? I actually have a "platinum" card, and I certainly don't have a platinum level of income!
Now I'm aware that some cards, such as the Centurion Card (aka a Black Amex), provide exclusive benefits, and that probably is a card where if you use it people go "whoa". (But with an AU $4,300 annual fee it would want to provide exclusive benefits!) But in terms of Gold/Platinum cards, they seem to be more and more common. I certainly don't think I'm served any differently if I use a Gold Card.
Wednesday, March 25, 2009
Credit cards, interest rates, plan of attack
My credit card interest rates are as follows:


I haven't updated my list of credit card debt as I usually only do it at the end of the month. But essentially:
- I received a 6 month balance transfer promotional rate offer (3.99%) for Card 2. As Card 2 only had about $1,500 available, last month I transferred that balance to Card 3 to free up the credit.
- Card 5 was my highest credit rate, so I transferred part of that to Card 3 last month and paid some off.
- I have now transferred the rest of Card 5's balance to Card 2, so have reduced the rate from 15.49% to 3.99% - but I HAVE to pay it off in 6 months.
So when I next update my credit card list, Card 5 will have a balance of $0 (I know this is mainly due to balance transfers, but since it has been sitting around $9K for some time it is a nice feeling to get rid of it!) and Card 2 will have a balance of close to $5K.
My plan of attack is:
- Pay off Card 1 (now down to about $1,500) - smallest balance and highest interest rate
- Pay off Card 2 - need to pay off within 6 months or the interest rate will increase dramatically. I first about tackling it first but I should be able to pay both Card 1 and Card 2 off within 6 months - and if worst comes to worst I am expecting my tax refund before the 6 months expires.
- Pay off Card 3
- Pay off Card 4 - low(er) interest rate for the life of the balance so out of my credit cards, this is my lowest priority.
Thursday, March 19, 2009
Balance Transfers
Why does it feel like banks are out to get you for everything you have?
I have recently put through a balance transfer from Card 5 to Card 2 (haven't updated my credit card list yet). The amount is now listed as owing on Card 2, but is still listed as being outstanding on Card 5! This has happened with other balance transfers before, it seems that it stays on both cards for a day or so. Very frustrating … as I’m sure I’m being charged interest on both amounts!
I have recently put through a balance transfer from Card 5 to Card 2 (haven't updated my credit card list yet). The amount is now listed as owing on Card 2, but is still listed as being outstanding on Card 5! This has happened with other balance transfers before, it seems that it stays on both cards for a day or so. Very frustrating … as I’m sure I’m being charged interest on both amounts!
Saturday, February 14, 2009
Credit card limits
The amount of credit card debt I have is scary. What is scarier is the amount of my credit card limits - i.e., the amount of debt I would have if I maxed out all my credit cards.

(I don't include my AMEX in my list of debts because it is paid off in full each month).

$54,900!!!!
(I don't include my AMEX in my list of debts because it is paid off in full each month).
Subscribe to:
Posts (Atom)